Upholstered or not? How the HTS code decides your duty
Two chairs can look like one collection and receive different customs treatment. Give the broker the construction details, then carry the confirmed cost into the quote and purchase order.
The OrderPilot team·
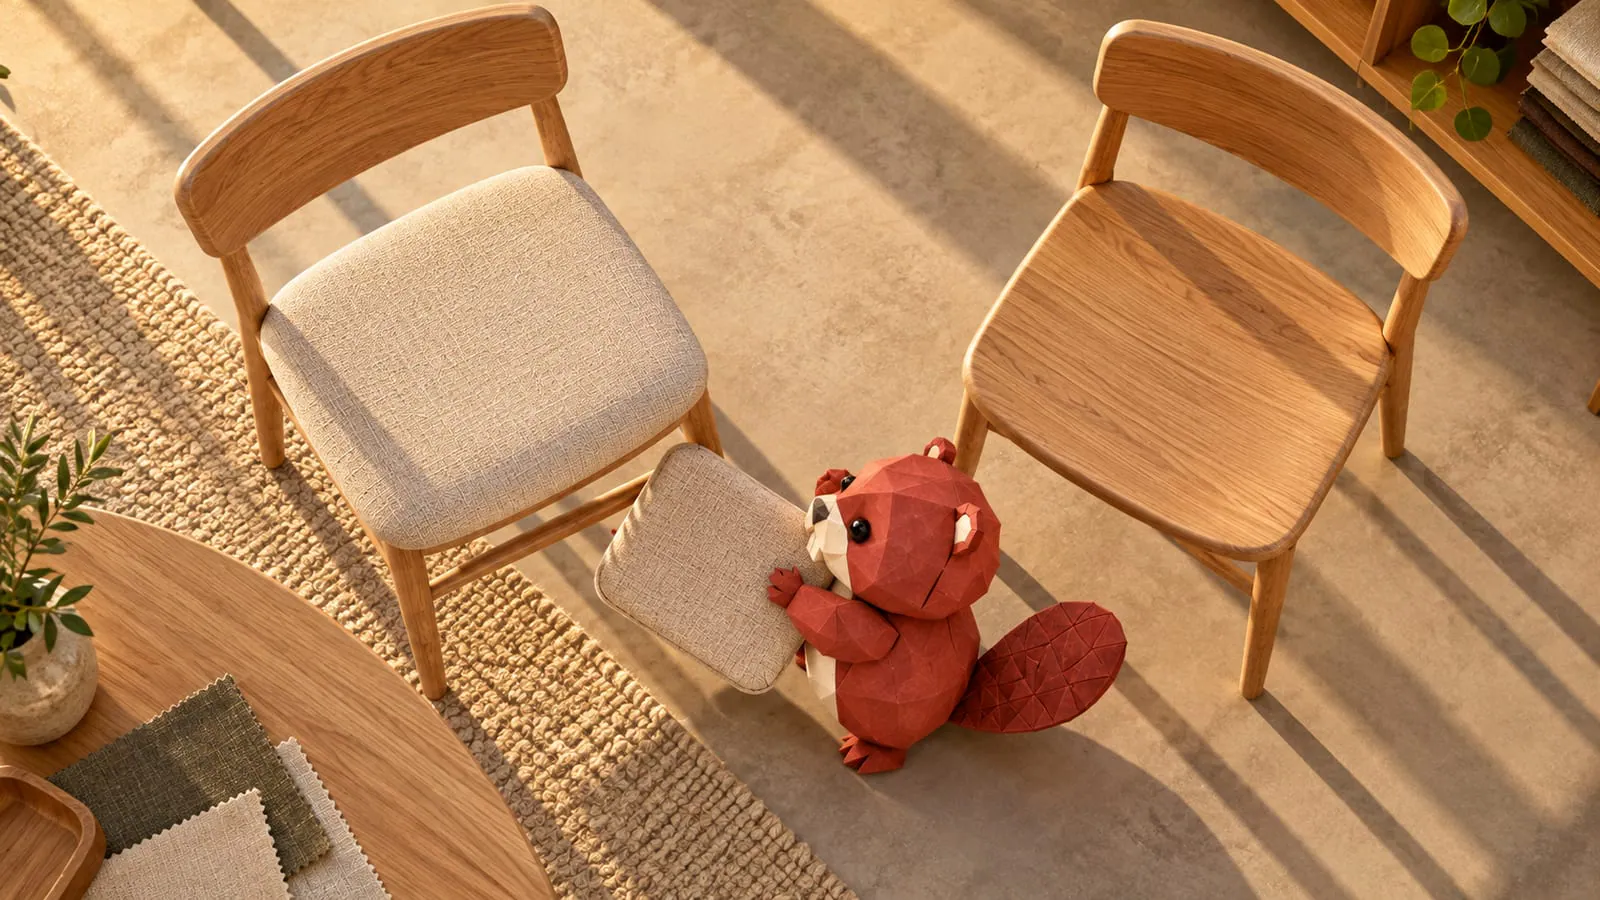
Two dining chairs share an oak frame and a factory. One has a padded fabric seat; the other is solid wood. Their collection name may be identical, but HTS classification can put them on different lines of the customs calculation.
The Harmonized Tariff Schedule classifies the goods being imported. For the Section 232 measure effective October 14, 2025, coverage follows specified tariff lines, not every product a showroom calls upholstered furniture. Start with the actual construction and imported form, then have the broker explain the classification and complete duty treatment.
General information, not legal advice.
Look below the furniture heading
The distinction is narrower than “furniture” or even “seating.” CBP's implementation guidance lists the covered upholstered wooden seating lines as 9401.61.4011, 9401.61.4031, 9401.61.6011, and 9401.61.6031. The general additional rate for those covered goods is 25%, with separate country treatment.
The proclamation also covers specified kitchen cabinets, vanities, and their parts. It does not make all goods in the broader furniture headings identical for tariff purposes. A customs entry needs the full supported classification, together with origin and any additional tariff provisions.
The Section 232 guide gives the broader rate picture. For a product outside the covered seating lines, ask for its ordinary duty and any other measures separately. “Outside this Section 232 line” does not mean “no duty of any kind.”
Take the ambiguous construction to the broker
The most useful classification question includes photographs, materials, and the form in which the product crosses the border. A description copied from the website may emphasize comfort while omitting the frame that determines the customs question.
| Product detail | Question to resolve |
|---|---|
| Wooden chair with a removable tie-on cushion | How is the complete imported article classified, and how does the loose cushion affect the analysis? |
| Metal-frame upholstered chair | Which seating line describes the frame and construction? |
| Bench with an upholstered top | What is its intended use and correct seating classification? |
| Bed with an upholstered headboard | How is the bed or separately imported headboard classified? |
| Outdoor seating with cushions | What materials, construction, and imported components matter? |
These are questions, not suggested rulings. Do not strip “upholstered” out of an invoice description to produce a preferred answer. The description should identify the actual goods clearly enough for the broker and customs to assess them.
A useful product packet also shows whether components travel together, whether the piece arrives assembled, and whether the factory has changed the frame. A swatch book is excellent at describing color. It is less forthcoming about what is underneath the seat.
See what the classification difference can cost
Say a shipment contains 40 chairs with an illustrative customs value of $250 each. If the broker confirms that they attract the 25% Section 232 seating charge, that component is $62.50 per chair, or $2,500 for the shipment. That is before any separately established charges.
For the wood-seat version, ask the broker for its actual classification and complete treatment. Do not invent an ordinary-duty rate merely to complete a comparison table. The useful worksheet has a confirmed figure or an unresolved field, not a plausible-looking percentage borrowed from another product or country.
| Example calculation | Upholstered version | Wood-seat version |
|---|---|---|
| Customs value per chair | $250 | Use the actual quoted value |
| Identified Section 232 component | $62.50 at 25% | Determine whether the provision covers the imported article |
| Ordinary and other duties | Broker's separate calculation | Broker's separate calculation |
| Full landed cost | Add freight and other acquisition charges | Add freight and other acquisition charges |
Compare the completed totals before making a sourcing or pricing decision. A product difference can change the duty, the manufacturing cost, and what the customer wants to buy. Keep those effects separate so a lower duty does not conceal a less useful product.
Know who is responsible for the classification
The vendor supplies product facts and may suggest a code. The broker helps prepare the entry and explain the classification. The importer retains its reasonable-care responsibilities under 19 U.S.C. § 1484, and customs administers and reviews the entry. A factory's familiar code is supporting information, not a substitute for the US analysis.
Ask the broker to document why the code fits the product and whether a prospective ruling is worthwhile for a recurring, uncertain model. 19 CFR § 177.2 calls for a complete statement of the transaction's facts and a detailed description of the article for classification requests.
You do not need to turn a sales associate into a customs filer. Assign the classification work to a licensed broker or other qualified customs professional and give them accurate evidence. The customs-brokerage guide helps define the service and the store's part in it.
An importer can make its own entry under the entry rules; using a broker does not transfer away the importer's responsibility. For a showroom without customs expertise, a broker is usually the practical choice even for a small shipment. Keep the broker's written classification explanation with the product specification so the next purchase starts with the same evidence.
Treat a design change as a fresh product review
A real construction change can change classification. Review the proposed design with the broker before using a different duty estimate in the buying decision. The entry must describe what is actually imported, not a future alteration the showroom hopes to make after arrival.
Keep the old and new specifications identifiable. If a vendor changes from a wooden frame to a different construction under the same model name, record the effective production version and affected orders. Purchasing and receiving need to distinguish those versions as well as customs does.
Origin is a separate question from classification. A correctly classified chair can still receive different treatment depending on where it originates. Use the country-of-origin guide to obtain the manufacturing facts without assuming the brand's headquarters settles the issue.
Review past mistakes with the entry records intact
If a classification appears wrong, gather the affected entries, product evidence, and the earlier reasoning. Contact the broker promptly. The available correction route depends on the entry's status and circumstances; changing a product description for future orders does not correct old entries.
19 U.S.C. § 1592 addresses material false statements or omissions involving negligence, gross negligence, or fraud, and provides for recovery of lost duties. Check with your attorney where a past-error review raises penalty or disclosure questions. Do not assume every error has the same consequence or that a disclosure is a simple formality.
Keep the review factual: which goods, which entries, which code, and what evidence changed the conclusion. Preserve the original records and any corrected versions. That gives the people resolving the issue a coherent history instead of a set of overwritten files.
Carry confirmed differences into OrderPilot
An OrderPilot template can represent a chair's seat choice, such as Upholstered or Wood, with its own cost. Use the confirmed product-cost assumptions when preparing quotes. The product-template guide explains how options preserve the configuration the customer selected. On the PO, record duty as a purchasing charge and apply it to the lines that incurred it. Keep the broker's breakdown attached. If costs on the template are estimates that already include a duty allowance, reconcile that allowance with the actual purchasing charge so it is not counted twice. OrderPilot records the configuration and cost; the broker establishes customs treatment. Once that treatment is settled, use the charge-allocation guide to give each received piece the cost it actually incurred.
Sources
- CSMS #66492057: Section 232 implementation — U.S. Customs and Border Protection, October 10, 2025; effective October 14, 2025.
- Proclamation 10976 — President of the United States, September 29, 2025.
- 19 U.S.C. § 1484 — United States Code, Cornell Legal Information Institute.
- 19 CFR § 177.2: Ruling requests — Code of Federal Regulations, Cornell Legal Information Institute.
- 19 U.S.C. § 1592: Customs penalties — United States Code, Cornell Legal Information Institute.
Give the broker the actual chair, in facts and photographs, before giving the buyer a duty estimate.













